Event submissions
Published
This submission belongs to the session S2. Machine Learning for Next-Generation Risk Modeling of the event The 2nd International Online Conference on Risk and Financial Management
Published date
28 Oct, 2026
Academic Editor
 Thanasis Stengos
Citation
Han Li, Xufeng Zhang, Does Global News Tone Add Predictive Value for Market Stress? Out-of-Sample Evidence from GDELT and the VIX, in Proceedings of The 2nd International Online Conference on Risk and Financial Management, 2 November–4 November 2026, MDPI: Basel, Switzerland
Share
Email
Facebook
Twitter
LinkedIn
Does Global News Tone Add Predictive Value for Market Stress? Out-of-Sample Evidence from GDELT and the VIX

Han Li 1
Xufeng Zhang 1
1. Resp AI Research Lab, CIIOE, Xiamen, Fujian 361000, China.
Abstract
Introduction: This study examines whether globally aggregated news tone adds stable out-of-sample information for forecasting U.S. market stress beyond observable financial-market conditions.
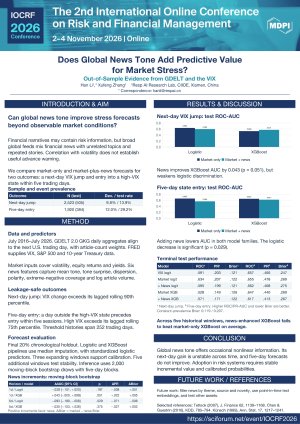
Methods: Daily GDELT 2.0 Global Knowledge Graph indicators were aligned with the spot Cboe VIX, S&P 500 returns, and the 10-year U.S. Treasury yield from July 2016 to July 2026. Two leakage-safe outcomes were modeled: (1) a next-trading-day VIX jump exceeding the lagged 90th percentile of daily VIX changes over the preceding 252 trading days, and (2) entry within five trading days into a high-VIX state defined by the lagged 75th percentile of the VIX level. Logistic regression and XGBoost were compared using chronological holdout testing, expanding-window validation, probability recalibration, and 2,000-replication moving-block bootstrap inference.
Results: For next-day stress, adding news reduced logistic ROC-AUC from 0.634 to 0.595, but increased XGBoost ROC-AUC from 0.528 to 0.571 (Δ = +0.043, 95% CI: −0.000 to +0.089; p = 0.051). This gain was marginal and did not persist across historical validation windows. For five-day state entry, news reduced logistic ROC-AUC from 0.655 to 0.562 (Δ = −0.093, 95% CI: −0.190 to −0.008; p = 0.029) and reduced XGBoost ROC-AUC from 0.647 to 0.617 (Δ = −0.030; p = 0.375). Direct tone effects and tone-by-regime interactions were not robust.
Conclusions: Broad global news tone does not provide a stable stand-alone early-warning signal. Its only suggestive incremental value appears in nonlinear next-day VIX-jump prediction, while five-day regime-transition forecasts are better explained by prevailing volatility and recent market dynamics. Risk managers should therefore use global news tone only as a supplementary, dynamically validated input.
Keywords
GDELT
VIX
market stress
news sentiment
XGBoost
out-of-sample prediction
Poster
IOCRF2026_GDELT_VIX_Poster.pdf
Patch-VTT: A Memory-Efficient Transformer for Volatility-Based Anomaly Detection and Risk-Off Portfolio Management
Mapping the Evolution of Machine Learning for Mortgage Repayment Prediction: A Bibliometric Analysis and Research Agenda for Automated Decision-Support Systems